
Free course · Module 9 · Investor profile
Charlie Munger
Charlie Munger combined broad learning, inversion and attention to incentives with a focus on business quality. Explore the reasoning behind his approach, test a claim from more than one angle, and see why conviction does not remove concentration risk.
Written by the StockEducation Editorial Team · Reviewed by Associate Professor Charles Lo, CPA, PhD · Updated 20 Oct 2026 · How we check lessons

Pick a topic to learn
Read in order, or return to the idea you need.
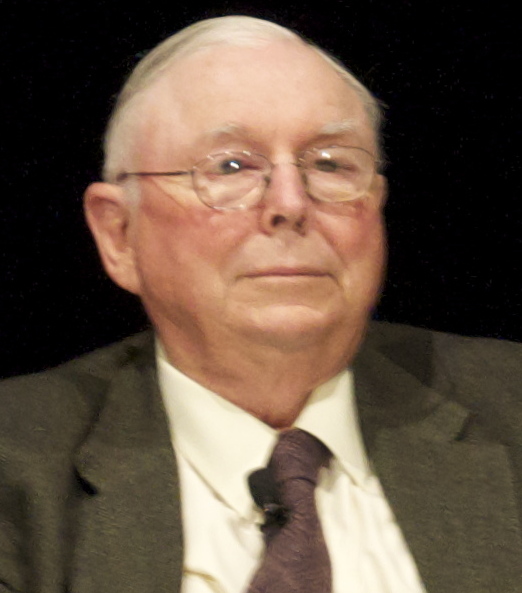
Warren Buffett’s longtime Berkshire Hathaway partner. This independent educational profile explains his ideas in our own words. Teaching lines are paraphrases, not claimed verbatim quotations or recommendations to copy his holdings.
Existing portrait: Wikimedia Commons image and attribution. Disclaimer · Terms of Use.Idea 1 of 4
Use more than one model.
A single useful explanation can become a blind spot when it is the only one you use. Munger’s mental-model approach draws ideas from several disciplines rather than forcing every problem into one framework. Source 1. For a business decision, economics can examine competition, accounting can test the reported numbers, and psychology can question the incentives behind a claim.
Use a model to generate a question you can investigate. Naming a bias or a scientific principle does not prove that it explains the case. Ask what evidence would support the explanation and what evidence would make you revise it.
Different viewpoints can reveal different ways a thesis could fail.
Why do customers choose this business, and what can competitors copy?
Do profits turn into cash, and what assets or obligations support them?
Who benefits from this claim, and what evidence might I prefer to overlook?
The explanation still has to fit the facts.
The person and the Berkshire partnership
Explain which model you are using, what it predicts and how you would check it.
Idea 2 of 4
Invert the problem before committing.
Instead of asking only how an idea could succeed, ask how it could go badly wrong. Inversion changes the search: identify failure conditions, then examine whether they are present or can be reduced. Munger discusses solving problems in reverse in his collected talks. Source 1.
Suppose a fictional company’s growth depends on one large customer. The upbeat question is whether sales can expand. The inverted question is what happens if that customer leaves, pays late or demands a lower price. Check the contract, customer concentration and financing needs before drawing a conclusion.
Then turn the concern into a concrete evidence check.
More customers, higher prices or larger orders may support the plan.
A lost customer, rising costs or debt due before cash arrives may undermine it.
Read the disclosure, assess its consequence and identify what remains unknown.
Inversion improves the questions; it cannot guarantee the outcome.
A short vocabulary for clearer thinking
Check incentives and seek contrary evidence
Write one plausible failure condition and the evidence needed to evaluate it.
Idea 3 of 4
Study the business, then the price.
Business quality includes how much capital is needed to sustain and grow earnings. Buffett’s 2007 letter explains See’s Candies as an example: Blue Chip Stamps bought it in 1972 for $25 million, while the business required $8 million of operating capital at the time. The letter reports $40 million required by 2007, an increase of $32 million. Source 3.
The purchase price, operating capital and later earnings are different measures. None is automatically an investor’s return. The case illustrates a question about business economics, not a rule that a famous brand is always a good purchase at any price.
Keep the measures separate before interpreting the result.
Price paid to acquire the business.
Capital required to conduct its operations, as described in the letter.
Capital required by the later reporting period: $32 million more.
Study working capital, assets, maintenance needs and competitive pressure.
Good economics, honest reporting and a sensible valuation need separate checks.
Patience, concentration and the price of being wrong
Read the examples without copying a portfolio
Understand the economics, the valuation and the downside before admiring a successful outcome.
Idea 4 of 4
See what concentration changes.
The same holding loss has a different portfolio effect at a different weight. Change one fictional holding’s starting share of a portfolio, then apply a price move to it. Everything else is assumed unchanged. This is one way to test the consequence of concentration without claiming to predict an actual loss.
A 40% position falling 50% reduces the whole portfolio by 20% under these assumptions. A 10% position with the same fall reduces it by 5%. The example is not a recommended allocation, probability estimate or full portfolio stress test.
One holding’s effect on the portfolio
Fictional price-only scenarioUse portfolio value from $1 to $1 billion with up to two decimal places, weight from 0% to 100% with up to one decimal place, and holding change from -100% to +100% with up to one decimal place.
$9,000.00 elsewhere, assumed unchanged
$500.00 ending holding value
The other holdings are assumed unchanged. Real holdings can fall together; this is not a maximum-loss estimate.
Starting holding = portfolio × weight ÷ 100. Holding change = starting holding × assumed price move ÷ 100. Ending portfolio = starting portfolio + holding change. Portfolio percentage change = holding change ÷ starting portfolio × 100. Uses unrounded values; dollars display to cents and percentages to two decimals. Very small amounts can round to $0.00. Assumes a fully paid long holding with no borrowing, derivatives, dividends, fees, tax, inflation, trading or rebalancing. Other holdings may be correlated and can also lose value. These limits are exercise bounds, not realistic forecasts or suitable allocations.
Turn the result into a question
- Compare the 10% and 40% examples. Explain why the holding has the same price move but a different portfolio consequence.
- Choose total loss. Describe what remains when one 40% holding becomes worthless and everything else stays unchanged.
- Write the missing question: what could happen to the other holdings at the same time?
For a deeper discussion of interacting biases, read Charlie Munger’s 25 Cognitive Biases. Bias awareness is a learning aid, not proof that a portfolio is safe.
A short practice routine
Knowing more about a holding does not make its portfolio weight harmless.
Quick check
Three quick checks. Feedback straight away.
Why use more than one mental model?
Choose an answer to see the explanation.
A holding starts at 40% of a portfolio and falls 50%, while everything else stays unchanged. What is the whole-portfolio change?
Choose an answer to see the explanation.
Which question best demonstrates inversion?
Choose an answer to see the explanation.
Review your takeaway card and the learning path
- Use several lenses. Connect economics, accounting and psychology to evidence.
- Invert the problem. Identify what could fail and investigate it.
- Separate quality from price. Business economics and valuation need different checks.
- Measure concentration. Conviction does not remove the consequence of a large holding’s loss.
Reading markers and these practice checks stay on this device. They do not mark the LMS lesson complete.
Sources and assumptions
- Poor Charlie’s Almanack: publisher’s web edition. Munger’s collected talks and biographical material; mental models, inversion, incentives and learning. Teaching lines on this page are paraphrases, not verbatim quotations.
- Berkshire Hathaway: 2023 shareholder letter. Buffett’s tribute to Munger confirms their 1959 meeting, his influence on business quality and his November 28, 2023 death.
- Berkshire Hathaway: 2007 shareholder letter. See’s historical acquisition and capital-requirement figures. This case is not current data or a reconstruction of shareholder returns.
- SEC Investor.gov: Asset Allocation and Diversification. Background on spreading exposure and the limits of diversification. Munger’s concentrated approach is not a recommendation for every learner.
- SEC Investor.gov: Behavioral Patterns of U.S. Investors. Background on active trading, ignored fees, disposition effect and inadequate diversification.
Sources checked 20 October 2026. This independent profile explains selected ideas, not the complete original talks or a verified list of verbatim quotations. No live holdings, personal allocation recommendation or promised return is presented. Local reading and quiz controls do not complete the LMS lesson.
StockEducation provides general education, not personal financial, tax or legal advice. Nothing here recommends a specific security. Investing involves risk, including loss of money you invest.


