
Investor Masterclass
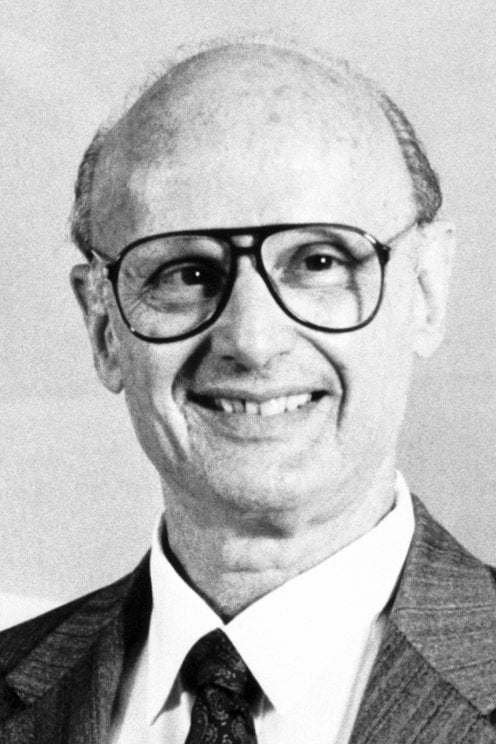
Harry Markowitz
The Economist Who Measured Diversification
Quick Answer
What do Harry Markowitz’s ideas teach investors?
Markowitz evaluates the whole portfolio using expected return and variance. Diversification depends on weights, each asset’s volatility and how returns move together. With positive weights, correlation below one can lower portfolio standard deviation relative to the weighted average of the assets’ separate standard deviations. It does not guarantee lower risk than every asset, a fixed return or protection from losses.
Start Here: The Short Version
Difficulty: Beginner to Intermediate
Big idea: Markowitz teaches that an investment should be judged by its effect on the whole portfolio, since holdings that move differently partly offset each other.
Use this lesson to understand the investor’s core idea first. Then use the examples, vocabulary, and application prompts to turn the idea into a practical investing rule.
Harry Markowitz was an economist whose 1952 paper, Portfolio Selection, put numbers on the advice to diversify rather than keep all your eggs in one basket. He shared the 1990 Nobel prize in economic sciences for pioneering work in financial economics. This page explains return, risk, correlation and the efficient frontier using made up numbers, then shows where the model falls short.
|
1952
Year Portfolio Selection appeared in The Journal of Finance
Volume 7, issue 1, pages 77 to 91
|
1959
Year he published his book on efficient diversification
Cowles Foundation Monograph 16, published by John Wiley & Sons
|
1990
Year he shared the Nobel prize in economic sciences
One third each with Merton Miller and William Sharpe
|
Figures as of September 2026.
Lesson ideas on this page are teaching lines written by our editors from Harry Markowitz’s published work and public interviews; they are not direct quotes. Figures reflect publicly reported records.
Key Takeaways
- Judge each investment by what it does to your whole portfolio, not by its own risk alone.
- In Markowitz’s model, risk is the spread of returns around their average, measured by variance.
- Diversification works through correlation: holdings that do not move in lockstep partly offset each other.
- The efficient frontier is the set of mixes with the highest expected return for each level of risk.
- Where you sit on the frontier depends on the risk you can bear, not on a formula.
- The model’s inputs are estimates, and estimation error can erase the gains from optimizing.
- Correlations across countries’ stock markets tend to rise in falling markets, so diversification can protect less in a crash.
From Chicago to the Nobel Prize
Harry Markowitz was born in Chicago in 1927, the only child of Morris and Mildred Markowitz, who ran a small grocery store. As a young man he read David Hume and Charles Darwin. At the University of Chicago he completed a two year bachelor’s program built around original texts. He then chose economics, drawn to the economics of uncertainty, and joined the Cowles Commission as a student member.
His dissertation topic grew out of an unplanned conversation that raised the idea of applying mathematics to the stock market. Reading John Burr Williams, Markowitz saw that maximizing expected return alone would mean owning a single security. Since sensible investors diversify, they must care about risk too. He chose variance to measure risk and saw that a portfolio’s variance depends on the covariances between its holdings.
His paper Portfolio Selection appeared in The Journal of Finance in March 1952, the year he joined the RAND Corporation. At James Tobin’s invitation, he spent 1955 to 1956 at the Cowles Foundation at Yale, where he wrote most of his 1959 book. In the early 1960s he returned to RAND to develop SIMSCRIPT, a simulation programming language. He later cofounded the company CACI with H. W. Karr.
He won the John von Neumann Theory Prize in 1989. In 1990, listed by the Nobel committee at the City University of New York, he shared the Nobel prize. In his later years he taught at UC San Diego’s Rady School of Management, and he died on June 22, 2023, at 95.
Career Milestones
1927 | Born in Chicago on August 24. |
1952 | Portfolio Selection appears in The Journal of Finance; he joins the RAND Corporation. |
1959 | Publishes Portfolio Selection: Efficient Diversification of Investments, written mostly at Yale. |
1962 | RAND publishes SIMSCRIPT, the simulation language he developed with Bernard Hausner and H. W. Karr. |
1990 | Shares the Nobel prize in economic sciences with Merton Miller and William Sharpe. |
2023 | Dies on June 22, aged 95. |
Three Influences
John Burr Williams’s The Theory of Investment Value Williams valued a stock as the present value of its future dividends. Reading it for his dissertation, Markowitz saw that judging by expected value alone would put all of an investor’s money into one security. Real investors spread their money around, so risk had to matter as well. That gap became the starting point of Portfolio Selection.
The Cowles Commission and Jacob Marschak As a Chicago student, Markowitz joined the Cowles Commission, a small research group directed by Tjalling Koopmans that included Marschak. He studied the economics of uncertainty with teachers including Milton Friedman, Marschak and Leonard Savage, and took Koopmans’s course on activity analysis. Marschak approved his stock market topic and sent him to Marshall Ketchum for a reading list in finance.
RAND and George Dantzig Markowitz joined RAND in 1952, and George Dantzig arrived soon after. Markowitz did not work on portfolio theory there. Still, the optimization techniques he learned shaped his later work on computing mean variance frontiers quickly. His simulation work at RAND and General Electric later led to SIMSCRIPT and to the company CACI.
Markowitz’s breakthrough came from asking why sensible people diversify at all, and then finding a way to measure the answer.
The lesson in one line
Portfolio Selection and the Efficient Frontier
Portfolio Selection judged a portfolio by two numbers, starting with expected return, the average result you anticipate. The second, variance, measures how widely results can scatter around that average; its square root, the standard deviation, is the figure usually quoted. The key step was showing that portfolio risk depends not just on each holding’s swings but on how the holdings move together. Statisticians measure that with covariance or, on a scale from minus 1 to 1, with correlation.
The illustration below uses made-up annual inputs rather than forecasts or real fund data. It assumes two assets with positive weights, no leverage and no fees or taxes. Expected returns and standard deviations use the same one-year period; the correlations are assumed rather than observed. Fund A is expected to return 10% a year with a 20% standard deviation, and Fund B 4% with a 10% standard deviation. Put 20% in A and 80% in B, and expected return is a simple weighted average, 5.2%, but risk is not. With unrelated funds, a correlation of zero, the mix’s standard deviation is about 8.9%, below Fund B’s; in perfect lockstep it is 12%.
Mixes with the highest expected return for each level of risk are called efficient, and on a chart they trace the efficient frontier. At zero correlation, a portfolio of Fund B alone sits below that curve. A mix of 40% A and 60% B has the same 10% standard deviation and a 6.4% expected return. The model does not choose for you; it clears away inefficient mixes and leaves you to pick the point that fits your risk tolerance.
The Framework
Markowitz’s approach rests on a small number of principles. These four do most of the work.
Risk and return as a pair
Markowitz noticed that an investor who cared only about expected return would hold just one security, the one with the highest expected return. Real investors diversify, so they must care about risk as well. His model therefore scores every portfolio on two numbers: expected return and variance. A fund shown only by its past return tells you half the story; the other half is how widely its results can swing.
Judge the whole portfolio
In Markowitz’s framework, the risk that matters belongs to the whole portfolio rather than to any single holding. A volatile asset can lower total risk if it tends to move differently from what you already own. A calm asset may add little if it moves in step with the rest. The practical test for any new holding is its correlation with your existing mix as well as its own swings.
Remove the inefficient, then choose
Markowitz’s method does not name one best portfolio. It removes any mix that another mix beats by offering more expected return for the same risk, or less risk for the same return. What remains is the efficient frontier. Choosing a point on it is a personal decision, based on your goals, your time horizon and the losses you can live with.
Treat inputs as estimates
The algebra is exact, but expected returns, volatilities and correlations must be estimated from past data or forecasts. In a 2009 test of 14 models across seven datasets, estimation error more than offset the gains from optimizing. Correlations also shift, and international stock markets tend to move together more in bear markets. Real US data shows both faces: in 2008 the S&P 500 returned negative 36.55% while the 10 year Treasury bond returned 20.1%, but in 2022 they fell together, negative 18.04% and negative 17.83%, our reading of the Damodaran data behind our S&P 500 Return Calculator. Use the framework to understand a mix, and favor mixes that still look sensible if your estimates are wrong.
The Markowitz Vocabulary
A small set of terms runs through Markowitz’s work. Learn these six and the rest of this page is easier to follow.
Expected return
The average return you anticipate across the possible outcomes. For a portfolio it is the weighted average of each holding’s expected return. In the illustrative example above, 20% in a fund expected to earn 10% and 80% in a fund expected to earn 4% gives 5.2%.
Variance and standard deviation
Markowitz’s measure of risk. Variance captures how widely returns scatter around their average; its square root, the standard deviation, is stated in percent and is easier to read. A fund with a 20% standard deviation swings far more than one at 10%. Both measures count surprise gains and surprise losses alike. Neither is a maximum-loss bound, and neither captures every credit, liquidity or inflation risk.
Correlation
A number from minus 1 to 1 that describes how two investments move together, derived from their covariance. For two positive-weight holdings with nonzero standard deviations, correlation of 1 makes portfolio standard deviation equal to the weighted average of their separate standard deviations. Below 1, it is lower than that average, but not necessarily lower than either asset’s volatility. This describes modeled variability, not a guaranteed loss limit.
Efficient frontier
The curve traced by the portfolios that offer the highest expected return for each level of risk. Any mix below the curve is inefficient, because another mix offers more expected return for the same risk. Markowitz framed the investor’s job as choosing from these best available combinations of risk and return.
Mean variance analysis
Markowitz’s method of choosing portfolios with two statistics: the mean, or expected return, and the variance, or risk. It looks for the mix with the lowest variance at each level of expected return. It became a foundation of what is now called modern portfolio theory.
Estimation error
The gap between the inputs you feed a model and their true values, which no one can know in advance. A 2009 study found that errors in estimated inputs more than offset the gains from mean variance optimization. The test used out of sample data, meaning data not used to build the models.
Notable Ideas
These six ideas explain why Markowitz’s work still matters to investors, along with the debates it started.
Portfolio Selection, 1952
Published in The Journal of Finance in March 1952, this paper argued that investors should weigh expected return against risk, measured by variance. Because a portfolio’s variance depends on how its securities move together, the paper gave diversification a logic that could be calculated rather than advised. It shifted the question from how risky a holding looks alone to how much risk it adds to the whole.
Efficient Diversification of Investments, 1959
Markowitz wrote most of this book at the Cowles Foundation at Yale in 1955 to 1956, at James Tobin’s invitation. He later wrote that without that invitation it might never have appeared. Its full title is Portfolio Selection: Efficient Diversification of Investments, and John Wiley & Sons issued it as Cowles Foundation Monograph 16. It moves from worked illustrations to the links between securities and portfolios, then to efficient portfolios and rational choice under uncertainty.
SIMSCRIPT, 1962
In the 1950s Markowitz saw that many practical problems called for computer simulation, and built logistics and factory models at RAND and General Electric. Back at RAND in the early 1960s he developed SIMSCRIPT, a language designed to cut the time needed to write simulation programs. RAND published it in November 1962 with Bernard Hausner and H. W. Karr. In 1989 the John von Neumann Theory Prize cited this work alongside portfolio theory and sparse matrix methods.
An even split to limit regret, 1998
In Money magazine in January 1998, Jason Zweig reported an account Markowitz gave in a late 1997 interview. Early in his career, Markowitz said, he skipped his own method when investing his retirement contributions. Picturing his regret if stocks soared without him or crashed with him all in, he split them evenly between stocks and bonds. In a 2009 Q&A with the Journal of Investment Consulting, he said he no longer used that split.
Correlations that rise in bear markets, 2001
Mean variance analysis takes correlations as fixed inputs, but real correlations shift. A 2001 Journal of Finance study by François Longin and Bruno Solnik applied extreme value theory to international stock markets. It found that correlation increases in bear markets, when protection matters most, but not in bull markets. In the illustrative example, a jump in correlation from zero to 1 would lift the 20/80 mix’s risk from about 8.9% to 12%.
Estimation error and the 1/N test, 2009
Victor DeMiguel, Lorenzo Garlappi and Raman Uppal tested the classic mean variance approach, and versions built to reduce estimation error. Their benchmark was the 1/N rule: split money equally across the N assets. Across 14 models and seven datasets, none was consistently better on the Sharpe ratio, a risk adjusted return measure, or on turnover. By their estimate, the classic approach would need around 3,000 months of data, some 250 years, to beat the equal split with 25 assets.
30 Simple Investor Lessons
This section turns Harry Markowitz’s best known ideas into simple teaching lines. Each line is a lesson summary written by our editors, not a direct quote. Check the evidence and limits before applying a teaching line.
Quote safety note: Treat these as educational principles, not verbatim quotes. For Harry Markowitz’s exact words, go to the primary sources listed at the end of this page.
Risk and Return Together
Lesson idea
Every return figure needs a risk figure beside it.
Means. Markowitz scored portfolios on expected return and variance, since a good average means little if the swings around it are too wide to bear.
Apply. For two funds you follow, write each one’s average annual return next to its worst calendar year, and compare the pairs.
Lesson idea
If return were all that mattered, you would own a single investment.
Means. Chasing the highest expected return alone points to one security, so the fact that careful people diversify shows they care about risk too.
Apply. List the reasons you hold more than one investment, and mark which of them are about avoiding a bad outcome.
Lesson idea
Risk is how far results can stray from the average, in either direction.
Means. Variance and standard deviation measure the spread of returns around their mean, counting large gains and large losses alike.
Apply. Look up standard deviations for two funds over the same dates, return frequency and annualization basis. Compare the values alongside a downside measure, rather than treating standard deviation as a worst-case loss.
Lesson idea
A higher expected return usually arrives with wider swings.
Means. In the illustrative example above, the fund expected to earn 10% has twice the standard deviation of the fund expected to earn 4%.
Apply. Before you compare two investments, write down the return you hope for and the worst year you could accept from each.
Lesson idea
One good year says little about the range of outcomes a mix can produce.
Means. Markowitz’s approach looks at the whole spread of possible results rather than the best or the most recent one.
Apply. In the StockEducation simulator or a paper portfolio, keep your own dated value series if available. Calculate return and peak-to-trough loss from consistent observations; use a spreadsheet for volatility if the simulator does not display it. Do not assume all these statistics are provided by the tool.
Correlation Drives Diversification
Lesson idea
Judge a new holding by what it does to the whole portfolio.
Means. A volatile asset can reduce total risk if it tends to move differently from what you already own.
Apply. Before adding a holding, write down which of your current investments it most resembles and why it might behave differently.
Lesson idea
Owning many things only helps if they do not all move together.
Means. Several funds that hold the same large companies can behave like one fund, so the number of holdings can overstate your diversification.
Apply. Enter two of your funds in the ETF Overlap and Fee Drag tool and note what share of their holdings they have in common.
Lesson idea
With positive weights, correlation below 1 can reduce modeled variability relative to the weighted average.
Means. For two positive-weight assets, the model’s portfolio standard deviation is below the weighted average of their separate standard deviations when correlation is below 1. This does not establish a maximum loss or guarantee lower risk than both assets.
Apply. For each pair of holdings, note whether you expect them to move together or apart, then check your guess against a year of prices.
Lesson idea
Diversify across the forces that drive returns as well as across names.
Means. Assets that respond to different forces, such as interest rates, consumer spending or commodity prices, are more likely to have low correlations.
Apply. Group your holdings by sector and by the main force behind their returns, and check whether one force dominates the list.
Lesson idea
A modest return can still earn its place if it steadies the whole.
Means. An asset with low correlation to the rest of a portfolio can lower total risk even when its own expected return is lower.
Apply. When reviewing a lower return holding such as a bond fund, record how it behaved in a year when stocks fell.
The Efficient Frontier
Lesson idea
Some portfolios are simply worse than others on both counts.
Means. A mix is inefficient when another offers more expected return for the same risk, or less risk for the same expected return.
Apply. Compare fictional portfolios using consistent expected-return and volatility assumptions, dates and constraints. A mix that is dominated on those inputs is inefficient in that model, but estimation errors and omitted risks can change the conclusion.
Lesson idea
There is no single best portfolio, only a best set.
Means. The efficient frontier holds many mixes, each the best available at its level of risk, and the final choice is yours.
Apply. Write down the largest one year loss you could live with, and use it to narrow your choices before you look at returns.
Lesson idea
Putting everything in the steadiest asset is not automatically the safest choice.
Means. At zero correlation, the illustrative 20/80 mix of the riskier and steadier funds beat the steadier fund alone on both return and risk.
Apply. If you hold mostly one asset type, sketch how a small slice of a less related asset would change your return and risk.
Lesson idea
Where you sit on the frontier is a personal choice that no formula can make for you.
Means. Two investors can both hold efficient mixes while choosing very different levels of risk, depending on their goals and time horizons.
Apply. Enter your age, risk tolerance, time horizon and goal in the Portfolio Allocation Calculator, then compare its illustrative split with your current mix.
Lesson idea
Extra risk is only worth taking if it buys extra expected return.
Means. Moving up the frontier trades more volatility for more expected return, while a change that adds risk without adding return moves you below it.
Apply. Before changing your mix, write down the extra return you expect in exchange for any extra risk, and your reason for expecting it.
Regret, Behavior and Simple Rules
Lesson idea
Even the creator of mean variance analysis once chose his own mix to limit regret.
Means. Jason Zweig reported that early in his career Markowitz split his retirement contributions evenly between stocks and bonds to avoid regretting either extreme.
Apply. Write down which would upset you more, missing a big rally or riding a crash fully invested, and keep the answer with your plan.
Lesson idea
A mix you can hold through bad years beats a better one you abandon.
Means. Portfolio math helps only if fear or regret does not push you out of the plan at the worst moment.
Apply. Before settling on an allocation, write what you would do if it lost a fifth of its value in a year.
Lesson idea
Simple rules deserve respect when the inputs are uncertain.
Means. In a 2009 study, none of 14 optimizing models beat an equal split consistently on new data, because estimation error ate the gains.
Apply. Compare any complex allocation you are considering with a simple equal split, and write down what evidence would justify the extra complexity.
Lesson idea
A famous anecdote is not a rule.
Means. Zweig has noted that the story is often misread as proof that equal splits are best, though Markowitz later moved on from it.
Apply. When you hear about a famous investor’s personal choice, find the original source and its date before drawing any lesson from it.
Lesson idea
Revisit your mix as your knowledge and circumstances change.
Means. By 2009 Markowitz said he had dropped the even split and divided his money across asset classes, following efficient portfolios he had seen.
Apply. Set one date each year to review your allocation, and record what has changed in your goals, income or time horizon.
What the Model Leaves Out
Lesson idea
Correlations can climb just when you need them to stay low.
Means. Longin and Solnik found that correlation between international stock markets increases in bear markets but not in bull markets.
Apply. When you judge how diversified you are, check how your holdings behaved in a falling market such as 2008, listed on our Stock Market Crash History page, as well as in calm years.
Lesson idea
The math is exact, but the inputs are guesses.
Means. Expected returns, volatilities and correlations come from past data or forecasts, yet the basic model treats them as known.
Apply. For any optimized mix you see, find the data period behind its inputs and note how a different period might change the answer.
Lesson idea
An optimizer is only as good as the numbers it is fed.
Means. In the 2009 study, errors in estimated inputs more than offset the gains from optimal diversification when models were tested on new data.
Apply. In the Portfolio Allocation Calculator, change one input at a time and note how much the illustrative split moves.
Lesson idea
Variance treats a surprise gain the same as a surprise loss.
Means. Standard deviation counts upside and downside swings equally, while most investors mainly worry about losses.
Apply. Next to the standard deviation of any fund you study, note its worst year and its largest peak to trough decline.
Lesson idea
Past relationships between assets are not promises.
Means. Correlations can shift over time, so a mix built on one period’s numbers may behave differently in the next.
Apply. Compare how two of your holdings behaved in a rising year and in a falling year, and note whether they moved together.
Putting It Into Practice
Lesson idea
Set the overall mix before choosing individual holdings.
Means. Markowitz’s approach judges each holding by its role in the whole, so the broad split between asset types comes first.
Apply. Write your target split between stocks, bonds and cash before researching any individual fund or stock.
Lesson idea
Rebalancing keeps the risk you chose from drifting.
Means. As prices move, a portfolio’s weights shift, and so do its expected return and risk.
Apply. Pick a rule, such as one review a year, for returning your mix to its target, and record each review in a journal.
Lesson idea
Diversification lowers risk; it does not remove it.
Means. When most assets share exposure to the same economy, some risk remains however many holdings you add.
Apply. Estimate what your portfolio might lose in a year when most assets fall together, and decide in advance how you would respond.
Lesson idea
Feel a mix’s swings with virtual money before real money.
Means. Watching a mix move through real market days shows how its ups and downs feel, which a table of expected values cannot.
Apply. Observe a fictional stock-and-bond mix on paper or in the simulator using your own notes. If comparable dated data is available, calculate return and drawdown and compare with an appropriate benchmark. A three-month trial does not validate an allocation or estimate its worst possible loss.
Lesson idea
Your tolerance for risk is the one input only you can supply.
Means. The efficient frontier shows the best available mixes, but choosing among them depends on your goals and your ability to sit through losses.
Apply. Write down when you will need the money and the largest yearly loss you could accept, and keep that page with your plan.
Final Reflections
Harry Markowitz gave diversification a way to be measured. His 1952 paper showed that risk belongs to the whole portfolio and that correlation decides how much a mix can cushion its parts. The sensible aim is an efficient mix matched to your tolerance for risk rather than a single best bet. Those ideas became a foundation of modern portfolio theory, and they explain why a mix can swing less than its parts on average.
His record also teaches humility about the tools. The inputs are estimates, correlations tend to rise in falling markets, and a 2009 study found estimation error can erase the gains from optimizing. Markowitz himself once chose a simple even split to limit regret, and later moved on from it. Use his framework to understand why a mix works, keep your inputs modest, and choose a risk level you can hold through bad years.
Five Commitments for the Disciplined Investor
- Judge every holding by what it does to the whole portfolio.
- Look at risk and return together, never return alone.
- Check how holdings move together before calling a portfolio diversified.
- Treat every model input as an estimate that could be wrong.
- Choose a level of risk you can hold through a falling market.
Sources Used for This Lesson
Editorial verification note. Investor quotations are risky because many popular lines online are paraphrased, shortened, or misattributed. To avoid that risk, this lesson presents teaching lines and investor lessons written by our editors, not verbatim quotes. The sources below allow readers to check historical claims and their context. Mathematical illustrations depend on their stated assumptions and are not promises of future performance.
Before using any line in ads, social posts, printed material, or legal or compliance sensitive pages, verify the exact wording against the primary sources below.
- Nobel Prize: Harry M. Markowitz, Biographical
- Nobel Prize: Harry M. Markowitz, Facts
- Nobel Prize: William F. Sharpe, Facts
- Nobel Prize: Merton H. Miller, Facts
- Harry Markowitz, Portfolio Selection, The Journal of Finance, Vol. 7, No. 1 (March 1952), pp. 77 to 91
- Cowles Foundation: Portfolio Selection, Efficient Diversification of Investments (Monograph 16)
- RAND Corporation: SIMSCRIPT, A Simulation Programming Language (November 1962)
- INFORMS: John von Neumann Theory Prize, past recipients
- Times of San Diego: UCSD Adjunct Professor Donates Nobel Prize Medal to Geisel Library (December 5, 2018)
- Jason Zweig: What Harry Markowitz Meant (October 2, 2017)
- François Longin and Bruno Solnik, Extreme Correlation of International Equity Markets, The Journal of Finance, Vol. 56, No. 2 (April 2001)
- Victor DeMiguel, Lorenzo Garlappi and Raman Uppal, Optimal Versus Naive Diversification: How Inefficient Is the 1/N Portfolio Strategy?, The Review of Financial Studies, Vol. 22, No. 5 (2009)
This lesson is for general financial education only. It does not provide personal financial advice, stock recommendations, or a guarantee of investment results.


